
Regulatory Capital Requirements: The Backbone of Banking Stability
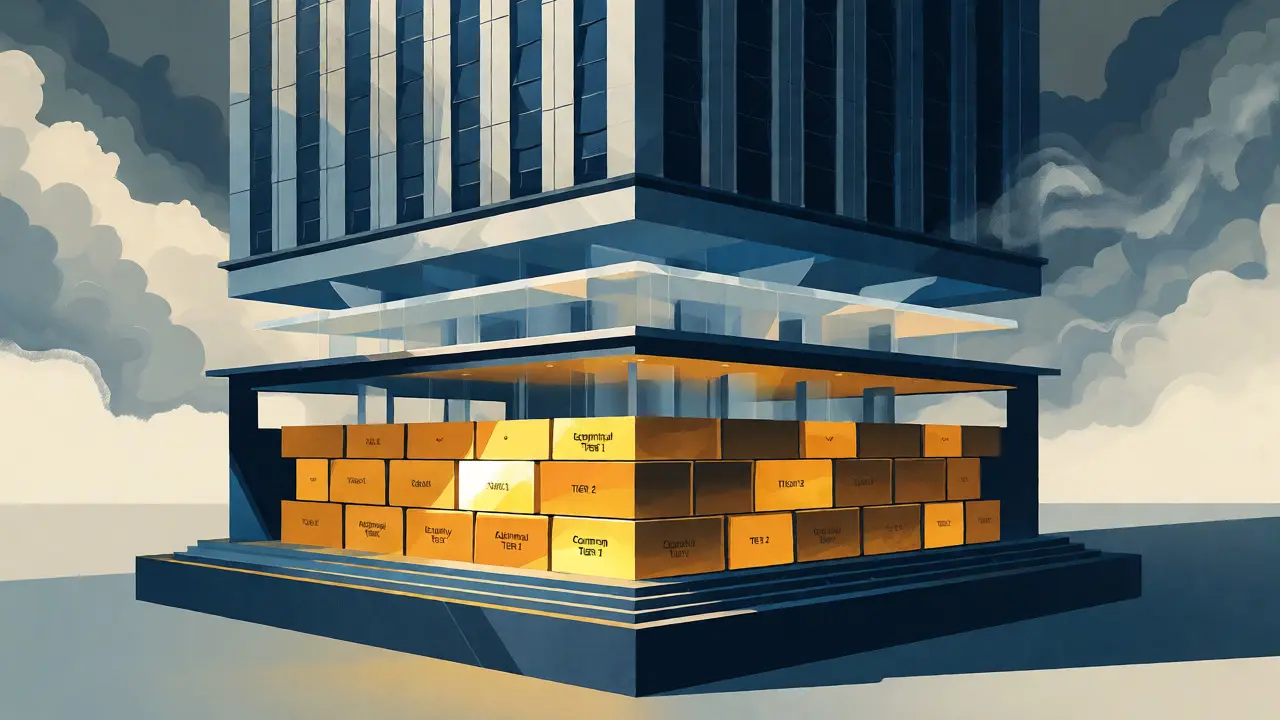
Think back to 2008. Banks were collapsing faster than we could read the headlines, and governments scrambled to plug holes with taxpayer money. Why did it happen? Largely because banks didn't have enough cash set aside to absorb losses when things went wrong. That gap between what banks thought they had and what they actually needed to survive a crisis is exactly what regulatory capital requirements are designed to fix. These aren't just bureaucratic red tape; they are the hard rules that dictate how much money a bank must keep in reserve to ensure it doesn't go bust when the economy takes a turn for the worse.
Why Do Banks Need Extra Cash?
At its core, regulatory capital is about safety margins. If you run a bakery, you don't spend every dollar you make on flour. You keep some aside for when the oven breaks or sales dip. Banks do the same thing, but on a massive scale. Basel III is the current global standard for these rules. It was finalized in 2017 and has been rolling out globally through 2027. Before this, rules were looser, which contributed heavily to the financial crisis. Today, regulators demand that banks hold high-quality capital-money that can truly absorb losses without forcing the bank to stop lending.
The primary goal here isn't just to protect depositors (though that's part of it). It's to prevent systemic failure. When one big bank fails, it can drag others down with it. By forcing banks to hold more capital, regulators aim to make the entire system more resilient. According to the Bank for International Settlements, the aim is to stop scenarios like the $426 billion U.S. bailout during the crisis. Essentially, if banks lose money on bad loans, they should use their own profits and reserves to cover it, not ask the public for help.
The Three Tiers of Capital Quality
Not all money sitting in a bank account counts as "capital" in the eyes of regulators. There’s a strict hierarchy based on how easily that money can absorb losses. This is where things get technical, but it matters because it determines how safe your bank actually is.
| Tier | Composition | Minimum Requirement (% of RWA) | Purpose |
|---|---|---|---|
| CET1 (Common Equity Tier 1) | Common shares, retained earnings | 4.5% (plus buffers) | Absorb losses while bank continues operating |
| AT1 (Additional Tier 1) | Perpetual preferred shares, hybrids | Combined CET1+AT1 ≥ 6.0% | Absorb losses via conversion to equity |
| Tier 2 | Subordinated debt (5+ year maturity) | Total Capital ≥ 8.0% | Absorb losses in bankruptcy (gone concern) |
Common Equity Tier 1 (CET1) is the gold standard. It consists of shareholders' equity and retained earnings. This is the highest quality capital because it absorbs losses immediately and unconditionally. If a bank writes off a bad loan, it hits CET1 first. Regulators love this because it means the bank owners take the hit, not the taxpayers.
Then there is Additional Tier 1 (AT1). This includes instruments like perpetual bonds. These are trickier. They don't count as pure equity until a trigger event happens, at which point they might convert into shares or be written down. Finally, Tier 2 capital acts as a last line of defense. It usually involves subordinated debt that only absorbs losses if the bank is already failing.
Risk-Weighted Assets: Not All Loans Are Equal
You might wonder why a bank holding government bonds needs less capital than one holding risky startup loans. The answer lies in Risk-Weighted Assets (RWA). Capital requirements aren't calculated against total assets; they're calculated against risk-adjusted assets.
Imagine two banks each lend $1 million. Bank A lends to the U.S. government (risk weight ~0%). Bank B lends to a volatile tech startup (risk weight 100-150%). Bank A needs almost no extra capital for that loan. Bank B needs significant capital to cover the higher chance of default. This system encourages banks to be cautious with risky investments. However, calculating RWA is complex. Banks can use standardized approaches set by regulators or internal models approved by supervisors. The latter allows for more precision but requires rigorous validation.
In 2023, European banks reported an average RWA density of 32.6%, while U.S. banks reported 45.8%. This difference highlights how different jurisdictions calculate risk. It also shows why comparing raw capital ratios across countries can be misleading unless you adjust for how they weigh risk.
Buffers Above the Minimum
Hitting the minimum requirement isn't enough. Regulators require banks to hold extra capital buffers. Think of these as shock absorbers. If a bank falls below its buffer, it faces restrictions on paying dividends or bonuses, but it isn't necessarily shut down. This gives management time to raise more capital or reduce risk.
- Capital Conservation Buffer: An additional 2.5% of CET1 required above the minimum.
- Countercyclical Buffer: Can range from 0% to 2.5%. Regulators raise this during economic booms to cool down lending and lower it during recessions to encourage credit flow.
- G-SIB Surcharge: Global Systemically Important Banks (like JPMorgan or HSBC) face extra charges ranging from 1.0% to 3.5% because their failure would hurt the whole world.
For most major banks, the effective minimum CET1 ratio ends up being around 7.0% to 10.5% when you add these buffers together. During the 2023 Federal Reserve stress tests, all participating banks maintained CET1 ratios above 8.0% even under severely adverse conditions. This suggests the framework is working to keep large institutions stable.
The Cost of Compliance and Real-World Impact
Compliance isn't free. For community banks, adhering to these rules can consume a huge portion of their budget. A survey by the American Bankers Association found that 68% of small banks spend over $1.2 million annually on capital compliance. That’s a lot of money that could otherwise go toward new branches or better customer service.
Larger banks spend billions on technology to track these metrics. JPMorgan Chase, for instance, invested $1.4 billion in technology for capital framework compliance between 2018 and 2022. But this spending buys stability. Citigroup noted that its robust capital framework allowed it to increase dividends by 10% during market volatility in 2022. So, while costly, strong capital positions allow banks to reward shareholders even when markets are shaky.
There’s a trade-off, though. Critics argue that high capital requirements make borrowing more expensive. Research from the Federal Reserve Bank of New York suggests that a 1 percentage point increase in capital requirements correlates with a 15-20 basis point increase in mortgage rates. So, safer banks mean slightly pricier mortgages for homeowners.
Emerging Challenges: Climate and Crypto
The current framework wasn't built for today's risks. Climate change poses physical and transition risks that traditional models miss. If a coastal city floods, property values drop, and banks' collateral loses value. Regulators are now working to integrate climate risk into capital calculations, with targets set for 2025.
Then there’s the rise of non-bank financial intermediation, often called shadow banking. Assets in this sector have grown to $184 trillion globally. Since many crypto-native firms and fintech lenders don’t face the same strict capital rules as traditional banks, there’s a risk of regulatory arbitrage. Money flows to places with lighter rules, potentially creating new pockets of instability that the Basel framework doesn't yet capture.
Key Takeaways
- Regulatory capital requirements are mandatory reserves banks must hold to absorb losses.
- Basel III is the current global standard, emphasizing high-quality equity (CET1).
- Capital is tiered: CET1 is best, followed by AT1 and Tier 2.
- Requirements are based on Risk-Weighted Assets (RWA), not just total assets.
- Banks must hold buffers above minimums to avoid dividend restrictions.
What is the minimum CET1 ratio required?
The base minimum for Common Equity Tier 1 (CET1) is 4.5% of Risk-Weighted Assets. However, when combined with mandatory buffers like the capital conservation buffer (2.5%), the effective minimum for most banks is closer to 7.0% or higher.
Why do banks need risk-weighted assets?
Risk-Weighted Assets (RWA) ensure that banks hold more capital against riskier loans. A loan to a stable government requires less capital backing than a loan to a volatile startup, reflecting the differing probabilities of loss.
Do regulatory capital requirements affect interest rates?
Yes. Higher capital requirements increase the cost of funding for banks. Studies suggest that a 1% increase in capital requirements can lead to a 15-20 basis point increase in mortgage rates for prime borrowers.
What happens if a bank breaches its capital buffer?
If a bank falls into its buffer zone, it faces automatic restrictions on distributing profits. This includes limits on dividends, share buybacks, and discretionary bonus payments until the buffer is restored.
How does Basel IV differ from Basel III?
Basel IV is essentially the finalization of Basel III reforms. Key changes include stricter limits on using internal models for risk calculation (the output floor) and revised methodologies for operational risk, aiming to reduce variability in risk-weighted asset calculations across banks.